Free guide · For UK credit unions

Build your AI lending strategy

What is actually working in credit union lending, the questions to ask before you buy, and what it really costs to run.

  • Where the sector actually is — filed accounts for 43 UK credit unions
  • The five use cases that are automated in production today
  • A business case your board and risk committee will accept
  • What it really costs to run, line by line

Get the guide

Four details and we’ll email it straight to your inbox.

Can’t see yours? Email hello@creditcanary.co.uk and we’ll add it.

By requesting the guide you agree we may contact you about it. We’ll never share your details. See our privacy policy.

Where the sector is

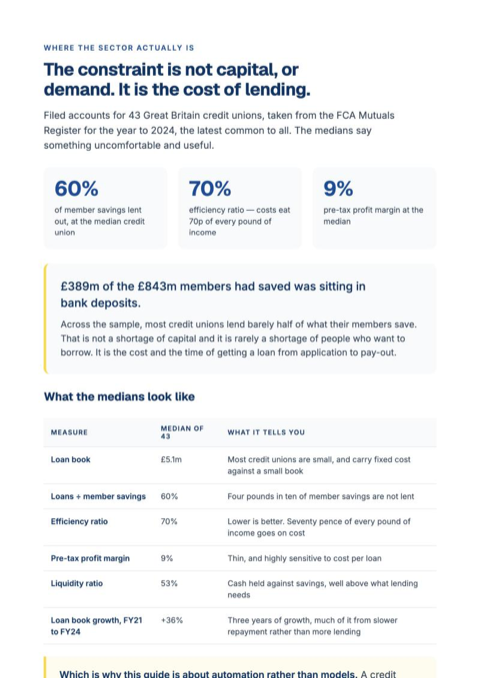
The constraint is not capital, or demand. It is the cost of lending.

£389m of the £843m members had saved was sitting in bank deposits. Across the sample, most credit unions lend barely half of what their members save — not for want of capital, or of people who want to borrow, but because of the cost and the time of getting a loan from application to pay-out.

60%
of member savings lent out
at the median credit union
70%
efficiency ratio
70p of every £1 of income goes on cost
9%
pre-tax profit margin
thin, and sensitive to cost per loan

Filed accounts for 43 Great Britain credit unions, FCA Mutuals Register, year to 2024 — the latest common to all.

Our position

The model never makes the decision. Your rules do. AI does the work around the decision — and that work is most of the cost.

Proof it works

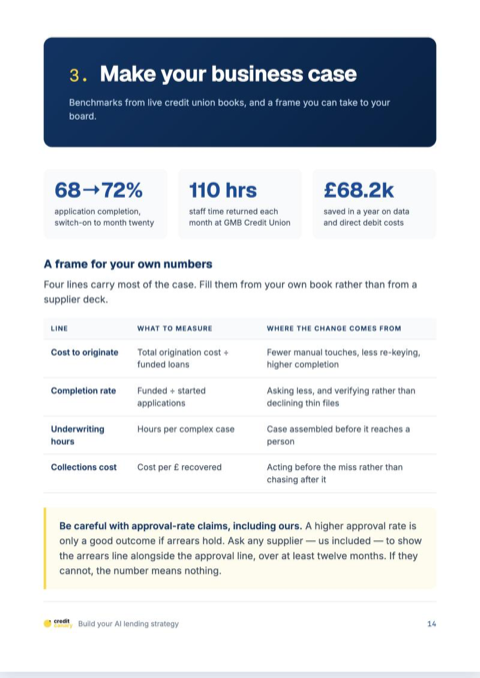
A record year at one credit union, with no extra staff or marketing

68→72%
application completion
from switch-on to month twenty
110 hrs
staff time returned a month
at GMB Credit Union
£68.2k
saved in a year
on data and direct debit costs alone
“Credit Canary gave us the infrastructure to grow without growing our team. Our growth is now driven by great systems and a wealth of data.”
Hans Billman, Chief Executive, GMB Credit Union

Completion figures are Credit Canary’s own, measured across live client books. The 45 to 55% comparison used later is our estimate of the sector range from client data, not an independently published benchmark. Hours and savings are GMB Credit Union’s reported year-end figures, published with their permission. Results vary by credit union, product and starting position.

What’s inside

Twenty-five pages, eight sections

1
Executive summary
Where AI has reached production, and what it means for your plan
2
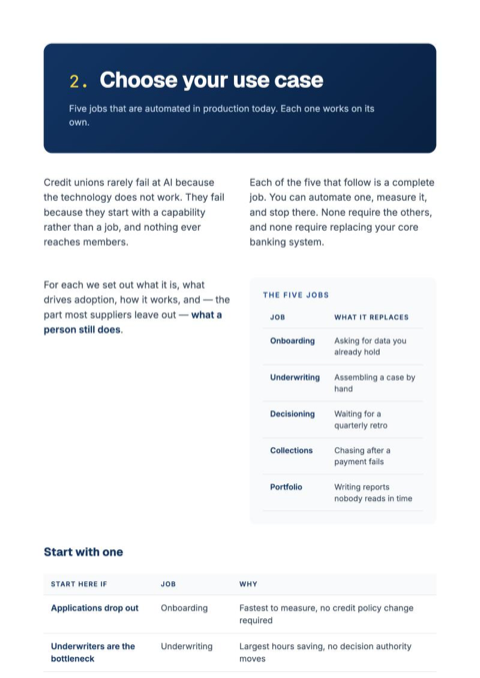
Choose your use case
Onboarding, underwriting, decisioning, collections, portfolio
3
Make your business case
Benchmarks from live books, and a frame for your own
4
Questions your board should answer
Seven things worth settling about any decisioning system
5
Get smart on cost
What you pay for, and the levers that move it
6
Select your delivery model
Buy, embed or build
7
Build your AI experience
Implementation guidance from our team
8
Your implementation checklist
Everything to settle before you start

How to read this. Sections 1 to 3 are for the board paper. Section 4 is the one to take to your compliance adviser. Section 5 is the one your treasurer will want. Sections 6 to 8 are for whoever has to deliver it.

A look inside
Guide cover Where the sector is Choose your use case Make your business case

Get your copy

The questions to ask, the five use cases, the business case, and what it really costs — free, for UK credit unions.

Email me the guide